What Is Sovereign AI Infrastructure? A Technical Guide to Requirements, Energy and the AI Factory Model
Sovereign AI infrastructure has moved from a policy slogan to a procurement category. Governments, regulated industries and large enterprises are now asking the same question their CIOs avoided for a decade: what does it actually take to train, fine-tune and serve frontier AI inside our own jurisdiction, on hardware we control, powered by energy we can account for?
This guide is the technical answer. It defines the term, lists the requirements, walks through the energy and cooling constraints, and explains the AI Factory model that has become the reference architecture for sovereign deployments in Europe and beyond.
What "sovereign AI" actually means
Sovereign AI is the capability to develop and operate AI systems under the exclusive legal, operational and physical control of a given nation, region or enterprise. It is not a single product. It is a stack of decisions across four layers:
- Silicon and compute — GPUs, accelerators, networking and storage physically located in the sovereign territory.
- Power and facility — grid connection, on-site generation, cooling and the data center shell that hosts the compute.
- Software and models — open-weight or licensed models, training frameworks, orchestration and inference runtimes that can be audited and modified.
- Data and governance — datasets, vector stores, logs and identity systems governed by local law, with no foreign extraterritorial reach (CLOUD Act, FISA 702, export controls).
If any of these four layers depends on a foreign provider whose government can compel disclosure or cut off access, the deployment is not sovereign. It is hosted.
Why "what is sovereign AI" is suddenly the question everyone asks
Three things changed between 2023 and 2026:
- Regulation caught up. NIS2, DORA and the EU AI Act now require demonstrable data residency, verifiable exit from critical providers, and documented data lineage for high-risk AI systems. Hyperscaler defaults no longer satisfy the text of the law.
- GPU supply became geopolitical. With ~90% of leading-edge logic fabricated in Taiwan and CoWoS packaging concentrated at TSMC, every AI roadmap is implicitly a bet on a single island. Diversifying *where* compute sits is the only available hedge.
- The economics inverted. At 2026 power prices, a well-sited on-premises AI Factory amortizes a €25–60M H100/H200 cluster in 24–36 months versus equivalent hyperscaler GPU-hour pricing. Sovereignty stopped being a premium and started being the cheaper option at scale.
Technical requirements: the short list
A deployment that can credibly be called sovereign AI infrastructure has to satisfy, at minimum:
- Dedicated accelerators. NVIDIA H100/H200/B200, AMD MI300X, or equivalent, with non-shared NVLink/InfiniBand fabrics. No multi-tenant time-slicing.
- High-bandwidth interconnect. 400G–800G InfiniBand NDR or RoCEv2 with non-blocking fat-tree or rail-optimized topology. Training scales with bisection bandwidth, not FLOPs alone.
- Parallel storage. 1–5 TB/s aggregate throughput from a parallel filesystem (Lustre, WEKA, VAST, DAOS) sized to keep GPUs above 90% utilization.
- Open-weight model stack. Llama 3, Mistral, Mixtral, Qwen or equivalent served via vLLM, TGI or Ollama, with the option to fine-tune on local data.
- Local vector and RAG layer. pgvector, Milvus, Qdrant or Weaviate co-located with the GPUs so retrieval latency does not dominate inference.
- Identity, logging and audit under local law. SSO, key management (HSM), and full prompt/response logging in storage that no foreign authority can compel.
Anything less and you are running a private deployment of someone else's stack.
The energy constraint nobody can engineer around
Compute is the headline; power is the binding constraint. A single NVIDIA DGX H100 node draws ~10.2 kW. A 1,024-GPU H100 cluster lands around 1.3–1.5 MW of IT load, which becomes 1.6–1.8 MW at the meter once cooling and conversion losses are included.
Three numbers define whether a site is viable:
- Connected power. Grid connection in MW, with a firm activation date. In Spain, Italy, Germany and Ireland, this is now the scarcest resource — multi-year queues are normal.
- PUE. Power Usage Effectiveness. Hyperscale greenfield in cool climates can hit 1.10–1.20; legacy enterprise sites sit at 1.6–1.9. Every 0.1 of PUE is ~10% of your opex.
- Carbon intensity. gCO₂/kWh of the local grid. Iberia, the Nordics and France land between 30 and 150 gCO₂/kWh; coal-heavy grids exceed 600. AI Act and CSRD reporting will increasingly price this in.
The practical implication: sovereign AI infrastructure is built where power is *available, clean and cheap simultaneously*. That is a much smaller map than the one most enterprises start with.
Cooling: why air is over for training clusters
H100 and B200 generations cross the rack-density threshold where air cooling stops working. A 40–60 kW rack is the new normal for training; B200 reference designs go to 120 kW. Two cooling architectures dominate sovereign builds:
- Direct-to-chip liquid cooling (DLC). Cold plates on GPUs and CPUs, warm-water loop at 30–45 °C, rear-door heat exchangers for the residual air load. PUE 1.10–1.20 achievable in temperate climates.
- Immersion cooling. Single-phase dielectric fluid, tank-based. Higher density still, simpler mechanical plant, but heavier ecosystem lock-in on server form factor.
Retrofitting a legacy enterprise data center to either is usually more expensive than building a purpose-designed AI hall next to it.
The AI Factory model
"AI Factory" is the term NVIDIA, the European Commission and most sovereign programs have converged on for the reference architecture. It is not a marketing word — it describes a specific operating model:
- A purpose-built facility sized in MW of IT load, not square meters.
- A single tenant or sovereign consortium owning the compute, not leasing slices of a hyperscaler region.
- A production line for models: continuous pre-training, fine-tuning, evaluation and inference, the way a semiconductor fab runs continuous wafer starts.
- End-to-end observability of energy, compute, data and model performance — so the unit economics of every trained or served token are known.
The shift from "data center" to "AI Factory" is the shift from real-estate thinking (lease me racks and power) to industrial thinking (run me a production line for intelligence). Sovereign AI infrastructure, in 2026, is almost always delivered in AI Factory form.
What it costs (order of magnitude)
For a reference 1,024 × H100 sovereign training cluster (~1.5 MW IT):
- Compute capex: €28–35M (GPUs, networking, storage, head nodes).
- Facility capex: €8–15M for a purpose-built 2–3 MW AI hall with DLC, depending on greenfield vs. brownfield.
- Annual energy opex: €1.5–3.5M at €60–140/MWh, before PPAs.
- Software and ops: €1–2M/year for a small SRE + MLOps team running the stack.
At those numbers, a sovereign AI Factory beats hyperscaler GPU pricing once utilization exceeds ~55–65%. Below that, the cloud is still cheaper — which is why most sovereign programs pair a baseline on-premises AI Factory with elastic burst capacity, rather than pretending the cloud disappears.
How to evaluate whether you need sovereign AI infrastructure
Four questions decide it:
- Is your data subject to NIS2, DORA, the AI Act, or sector rules (banking, defense, health, energy) that require demonstrable EU residency and exit?
- Would a foreign government's compelled-disclosure regime over your current provider create unacceptable risk?
- Are you running enough sustained AI workload (>50% utilization of a multi-MW cluster) for the unit economics to favor on-premises?
- Do you have, or can you secure, the power and the site?
Three "yes" answers and sovereign infrastructure is the right architecture. Four "yes" answers and it is the only architecture.
Where this goes next
The sovereign AI conversation in 2026 is not "should we?" It is "where, with what power contract, on which open model, and how fast can we energize?" The technical answers are settled. The remaining work is industrial: building the AI Factories, securing the megawatts, and turning regulated industries and governments into operators of their own intelligence — not tenants of someone else's.
That is the work BtMData exists to do, and the reason "what is sovereign AI infrastructure" stopped being a definition question and started being a deployment question.
Related Articles
What is a Data Center? The Five Pillars of Europe's Digital Future
Data centers are the backbone of the digital economy — the factories of the 21st century — representing a market worth over $1 trillion globally.
Why Edge Data Centers Are the Missing Link in Europe's Digital Infrastructure
European data center power demand will nearly triple by 2035. Edge data centers offer faster deployment, heat reuse, and strategic flexibility to meet this demand without collapsing grids.
Powering AI: Energy Systems Under Strain & the OpenAI Demand Surge
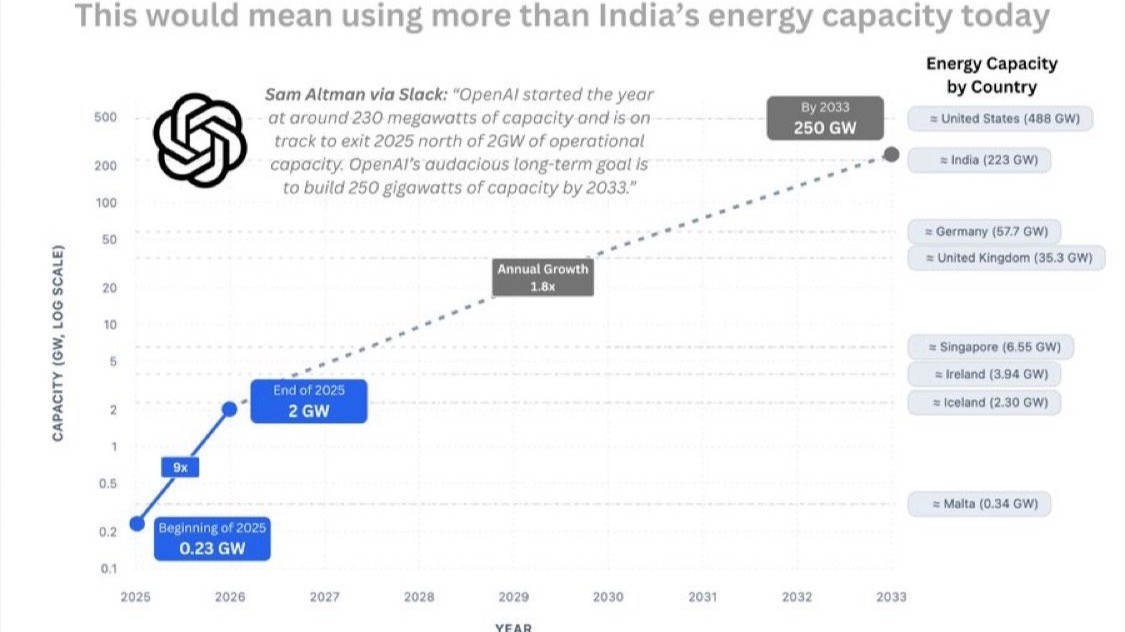
OpenAI has 9x'd their capacity this year, with a goal to 125x further by 2033, exceeding current energy capacity of India.